
Last updated: July 2026
Yes, Some South Carolina Buyers Close With $0 Down: Here's How
The 20% down payment idea is so common that many buyers talk themselves out of homeownership before they ever pick up the phone. Here is what that assumption misses: some South Carolina buyers close on a home with nothing out of pocket. Not every buyer. Not every loan. But for the right borrower in the right situation, $0 at closing is a real outcome, not a marketing gimmick.
Two government-backed programs, VA loans and USDA loans, allow qualified buyers to purchase with no down payment at all. A third path uses an FHA loan combined with gift funds and seller contributions to get some buyers to the table with $0 out of pocket, even though FHA itself requires a minimum 3.5% down. Which path fits depends on military eligibility, property location, household income, and credit profile. For a side-by-side comparison of every $0-down and low-down-payment route, see our full breakdown of no down payment options in South Carolina.
TL;DR: The Short Version
- VA loans and USDA loans are the 2 true $0 down mortgage paths for qualified South Carolina buyers.
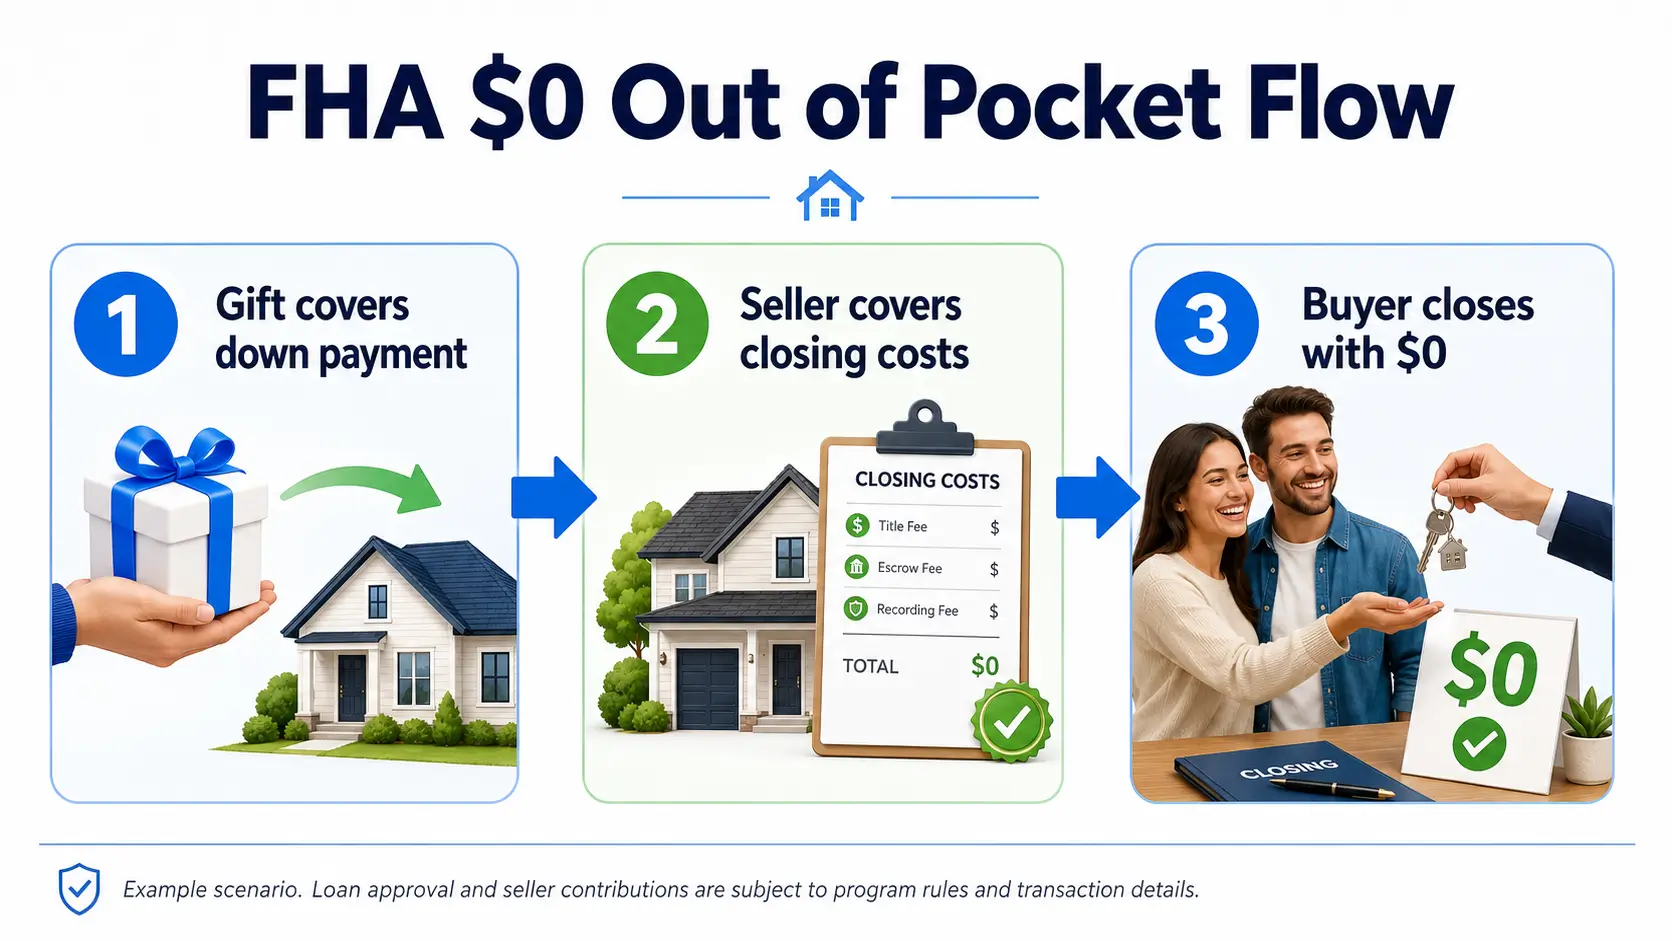
- FHA loans require 3.5% down, but gift funds from a family member can cover the down payment and seller contributions can cover closing costs, leaving some buyers with $0 out of pocket at closing.
- "No money down" is not the same as no cost. Mortgage insurance, guarantee fees, and a larger loan balance are real tradeoffs to understand.
- Which path fits depends on military eligibility, property location, income, and credit profile. No single program works for everyone.
- A custom rate quote from a licensed mortgage broker is the fastest way to find out which option applies to your situation.
VA Loans: The Strongest $0 Down Option for Military Buyers
For eligible veterans, active-duty service members, and qualifying surviving spouses, a VA loan is the most straightforward path to $0 down homeownership. There is no required down payment for buyers with full entitlement. Unlike most other low-down-payment programs, VA loans do not require private mortgage insurance at any loan size.
That last point matters more than it sounds. PMI on a conventional loan with less than 20% down can add hundreds of dollars to a monthly payment. VA buyers skip it entirely, which means more purchasing power and a lower monthly cost from day one. VA loans also carry no prepayment penalties, and the benefit is reusable across a lifetime as long as entitlement requirements are met.
In South Carolina, VA loans carry particular weight in military markets. Beaufort, Parris Island, and the surrounding Lowcountry have some of the highest VA loan volume in the state, and most sellers and listing agents in those markets understand how VA financing works. According to Military.com, VA loan rates are typically 0.25% to 0.5% below conventional rates.
VA Funding Fee at a Glance
There is a one-time funding fee. It can be rolled into the loan so it does not have to come out of pocket at closing. Borrowers with a verified VA funding-fee exemption are exempt from the fee entirely, and that exemption applies no matter how many times they have used their VA loan benefit before.
| Borrower Type | First Use | Subsequent Use |
|---|---|---|
| Down payment less than 5% | 2.15% | 3.3% |
| Down payment 5–9.99% | 1.5% | 1.5% |
| Down payment 10% or more | 1.25% | 1.25% |
| Disability-exempt veterans | 0% | 0% |
We have seen firsthand what happens when a VA loan is handled by someone who does not know the program. A borrower came to us after another broker dropped the ball on a VA file. The previous lender was not a VA specialist, the loan stalled, and the borrower was told it could not be done. We took over the file, worked with our lender relationships, and funded the loan. A "no" from the wrong lender is not always the final answer.
To use a VA loan, buyers need a Certificate of Eligibility, which a VA-approved lender can typically pull electronically during the application process. Eligibility is based on service history, discharge status, and entitlement availability. Borrowers also need to qualify based on income, credit, and lender underwriting guidelines.
One thing that surprises a lot of VA buyers: the program does not qualify borrowers off a hard debt-to-income ceiling the way most conventional guidelines do. VA underwriting looks at residual income, what is left over each month after debts, taxes, and living expenses. That approach can work in favor of a buyer with student loan payments or other debt who might get turned away under a stricter DTI-only rule.
USDA Loans: $0 Down for Buyers Outside the City Limits
The USDA Single Family Housing Guaranteed Loan Program offers 100% financing for buyers in eligible rural and suburban areas of South Carolina who meet income requirements. No down payment required. According to USDA Rural Development, the program assists approved lenders in providing low- and moderate-income households the opportunity to own adequate, modest, decent, safe, and sanitary dwellings as their primary residence in eligible rural areas.
A lot of buyers hear "rural" and assume USDA does not apply to them. That is often wrong. USDA-eligible areas in South Carolina include many communities that feel suburban, not rural. The way to check is simple: use the official USDA eligibility map and enter the property address. If the address qualifies, the location requirement is met.
USDA Loan: At a Glance
| Feature | Detail |
|---|---|
| Down Payment | 0% |
| Income Limit | Household income cannot exceed 115% of area median income |
| Property Requirement | Must be in a USDA-eligible area (check the eligibility map) |
| Loan Term | 30-year fixed only, no adjustable-rate option |
| Upfront Guarantee Fee | 1% of loan amount, can be financed into the loan |
| Annual Fee | 0.35% of remaining loan balance, built into monthly payment |
| Credit Score | No program minimum, but individual lenders may set their own overlays |
Income limits vary by county and household size, so the exact threshold depends on where you are buying and how many people are in the household. For buyers who fit the eligibility requirements, USDA loans are one of the most cost-effective paths to homeownership available in South Carolina.
Where USDA Eligibility Actually Falls in South Carolina
The city core in most South Carolina markets is too dense to qualify, but the areas just outside it often are not. Beaufort's downtown falls outside the program, while much of the surrounding county often qualifies. The same pattern holds in Charleston, where the urban core is excluded but the suburban fringe frequently qualifies, and in Columbia, where Chapin, Blythewood, and outer Lexington County are common eligible pockets. Greenville buyers see similar results toward Fountain Inn and Travelers Rest, and Myrtle Beach buyers often find eligibility once they move toward outer Horry County and Conway. The only way to know for certain is to run the exact address through the eligibility map above.
USDA's fees also run lower than FHA's over time. On a $280,000 purchase, USDA's 1% upfront guarantee fee plus 0.35% annual fee typically saves a buyer around $66 a month compared to FHA's 1.75% upfront and 0.55%–0.85% annual mortgage insurance, roughly $792 a year in a buyer's pocket for as long as the loan is held.
No VA or USDA? FHA With Gift Funds Can Still Get You to $0 Out of Pocket
If VA and USDA are off the table, FHA is usually the next conversation. FHA loans require a minimum 3.5% down payment for qualified borrowers with a credit score of 580 or higher, up to South Carolina's 2026 FHA loan limit of $541,287 in every county. On a $250,000 purchase, that 3.5% is $8,750. For a buyer without that saved up, the question becomes where the money comes from, and the answer for some buyers is: not from their own savings.
FHA allows two tools that, when used together and structured correctly, can get a buyer to the closing table with $0 out of pocket. They are separate mechanisms with separate rules, and both have to be handled correctly to work.
How Gift Funds Work With FHA
FHA allows the entire 3.5% minimum down payment to come from a documented gift from an eligible donor: a family member, close friend, employer, or certain governmental agencies. The gift cannot have repayment strings attached. To document it, the donor provides a signed gift letter with their name, relationship to the buyer, the amount being given, and a clear statement that no repayment is expected. The lender will also verify the transfer with a paper trail showing the funds moving from the donor's account to the buyer's account. One thing gift funds cannot do: they cannot come from the seller or anyone with a financial interest in the transaction.
How Seller Contributions Cover Closing Costs
FHA allows sellers to contribute toward a buyer's closing costs, up to 6% of the home's purchase price. Seller contributions cannot be used toward the down payment, only toward closing costs and prepaid expenses. When gift funds cover the down payment and seller contributions cover the closing costs, some buyers reach the table with nothing out of pocket.
Gift funds cover the down payment. Seller contributions cover closing costs. They cannot be swapped. The seller cannot cover the down payment, and gift funds cannot be used to offset seller-paid closing costs. Both must be documented correctly or the loan will not close.
Example: $0 Out of Pocket With FHA
| Item | Amount |
|---|---|
| Purchase Price | $250,000 |
| FHA Minimum Down Payment (3.5%) | $8,750 |
| Covered by Family Gift | $8,750 |
| Estimated Closing Costs | $7,500 |
| Covered by Seller Contribution | $7,500 |
| Buyer's Cash at Closing | $0 |
This is a real scenario. It requires the right loan structure, the right documentation, and a seller willing to negotiate. It is not automatic, and it does not happen on every deal. Every borrower still needs to qualify; the specifics depend on the full file, the property, the lender, and current program guidelines.
What "$0 Down" Actually Costs Over Time
Every low-down-payment path carries tradeoffs. A buyer who closes with nothing out of pocket starts with no equity: the loan balance equals the full purchase price. That is not a reason to avoid these programs, but it is a reason to understand the full picture before committing to a loan structure.
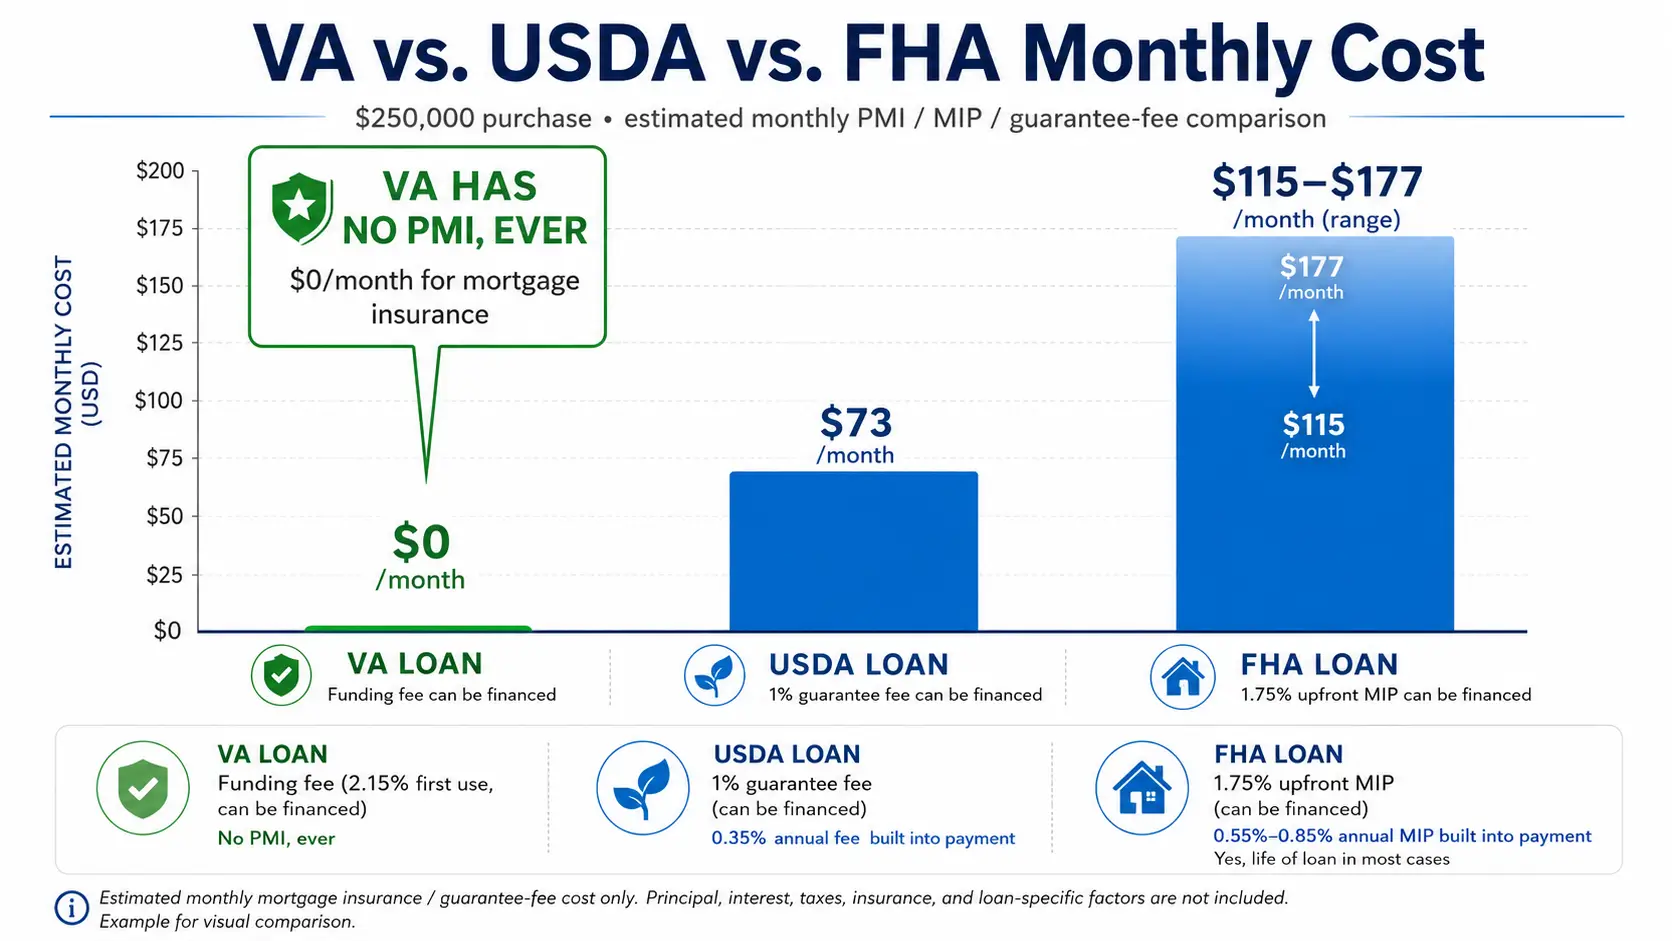
| Program | Upfront Cost | Ongoing Monthly Cost | PMI / MIP? |
|---|---|---|---|
| VA Loan | Funding fee (2.15% first use, can be financed) | None beyond P&I and taxes | No PMI, ever |
| USDA Loan | 1% guarantee fee (can be financed) | 0.35% annual fee built into payment | No traditional PMI |
| FHA Loan | 1.75% upfront MIP (can be financed) | 0.55%–0.85% annual MIP built into payment | Yes, life of loan in most cases |
With VA loans, certain borrowers, including veterans receiving VA disability compensation, may be exempt from the funding fee entirely. With FHA loans, the monthly MIP continues for the life of the loan in most cases, depending on the down payment and loan term. That is a meaningful long-term cost that buyers should factor into their monthly budget before choosing a program.
Which No-Down Loan Fits Your South Carolina Situation?
It comes down to four things: military eligibility, property location, household income, and credit profile. Here is a practical framework for most South Carolina buyers.
Military Eligible
- Start with VA loans in South Carolina: best combination of $0 down, no PMI, and competitive rates.
- The benefit is reusable across a lifetime as long as entitlement requirements are met.
- Disability-exempt veterans pay no funding fee at all.
Buying Outside a Major City
- Check the USDA eligibility map before assuming the property does not qualify.
- If the address qualifies and household income fits, USDA loans in SC are one of the most cost-effective paths available.
- 30-year fixed rate only, giving buyers payment stability from day one.
Neither VA nor USDA
- FHA loans in South Carolina with gift funds covering the down payment and seller contributions covering closing costs can get some buyers to $0 out of pocket.
- Requires the right deal structure and documentation; it is a legitimate path, not a guarantee.
- Strong credit buyers with some savings should also compare conventional loans at 3% down, useful up to South Carolina's 2026 conforming loan limit of $832,750, to see which costs less over time.
- First-time buyers weighing every option side by side can also start with our first-time homebuyer guide.
For a full breakdown of every loan program available to South Carolina buyers, the South Carolina home loans overview covers each option in detail.
Why Work With Beaufort Lending on a $0 Down Purchase
Benji Gecy launched his lending career in 1997 and has been recognized as a Top 1% mortgage broker nationally for five consecutive years. When you work with Beaufort Lending, you are not getting a single bank's rate sheet. You are getting wholesale lender shopping across dozens of options, with someone who works VA, USDA, and FHA files every week. Beaufort Lending consistently offers mortgage rates below the national average, and qualified buyers can reach the closing table in as little as 12 to 15 days.
With 168 five-star Google reviews as of May 2026, the track record speaks for itself. Get an instant rate quote anytime, day or night, at beaufort.mortgage/instant-rate-quote, or chat with our team (Opens in Messenger) if you have questions before you are ready to pull a quote.
Not sure which program you qualify for?
Tell us your situation and we will tell you which paths are open to you and what the real numbers look like. No commitment required.
Get a Free Rate Quote (Web)Frequently Asked Questions
Does USDA loan eligibility cover suburban South Carolina areas?
Often yes. Many communities that feel suburban fall inside USDA-eligible boundaries. Enter the property address in the official USDA eligibility map to confirm. Don't assume ineligibility before checking. Full USDA loan details →
Can FHA gift funds cover the entire down payment in South Carolina?
Yes. FHA allows the full 3.5% minimum down payment to come from a documented gift from an eligible donor. It must be a true gift with no repayment strings, and cannot come from the seller. Full FHA loan details →
What is the VA funding fee in South Carolina and can it be waived?
The standard fee for a first-time VA buyer with no down payment is 2.15% and can be rolled into the loan. Borrowers with a verified VA funding-fee exemption are typically exempt from the funding fee entirely. Full VA loan details →
Is FHA a better $0 down option than conventional loans in South Carolina?
It depends on credit and savings. FHA with gift funds can get some buyers to $0 out of pocket, but FHA mortgage insurance usually lasts the life of the loan. Conventional loans allow down payments as low as 3% and let PMI drop off once a buyer reaches 20% equity, which can cost less over time for stronger-credit borrowers. Full conventional loan details →
Find Out Which $0 Down Path Fits Your SC Situation
A lot of South Carolina buyers sit on the sideline because they assume they cannot afford to buy. Sometimes that is true. Often, it is not. The fastest way to find out is to get your scenario reviewed: real numbers, real programs, no obligation.
Find Out Which $0 Down Path Fits Your SC Situation
Get a custom rate quote in minutes, calculate your payments, or just reach out with questions.
Get Instant Rate Quote (Opens in Messenger) Get Rate Quote (Web)Other Resources You May Find Helpful
