Pre-Qualification Basics
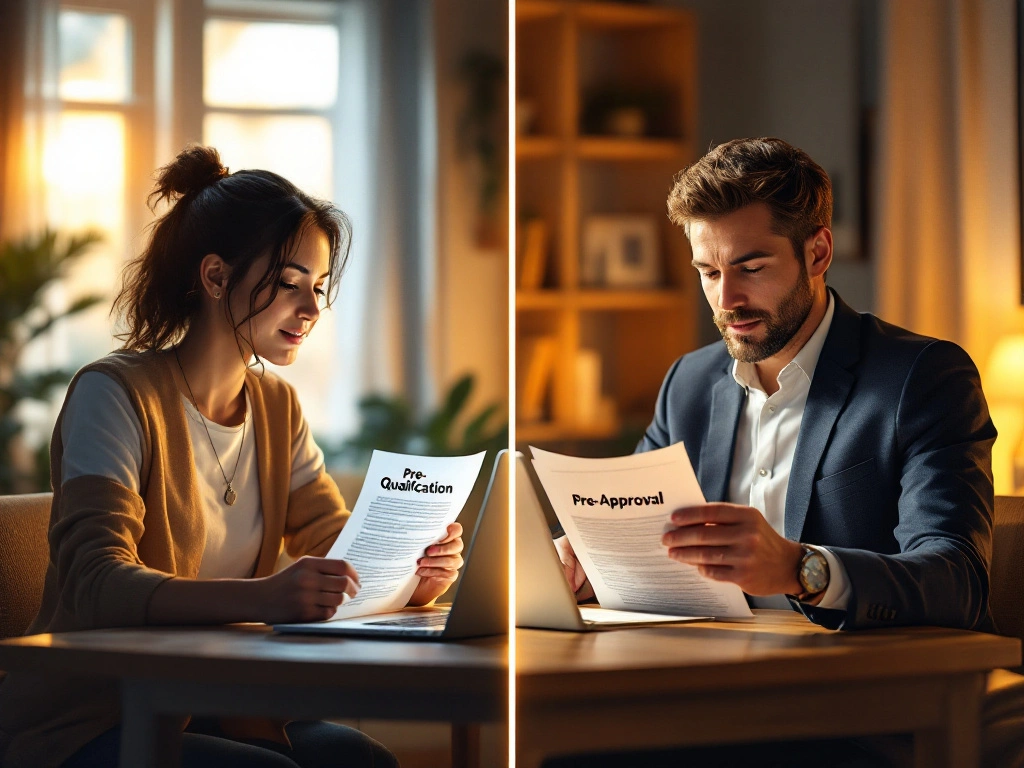
Think of pre-qualification as dipping your toe in the water. It’s a quick estimate of how much you might be able to borrow, based on:
- Your reported income and assets
- Expected down payment
- A soft credit check (no score impact)
You can often complete this step online in under an hour. Because it doesn’t require pay stubs or tax returns, pre-qualification is more of a conversation starter than a final verdict. Still, it’s a great way to get an early sense of your budget before touring Charleston homes.
Pre-Approval: The Serious Step
A pre-approval is where things get real. Lenders will do a deep dive into your financial picture, which means you’ll need to submit:
- Government-issued ID
- Pay stubs (last 30 days)
- W-2s or tax returns (two years)
- Bank statements (two months)
- A full list of monthly debts
Unlike pre-qualification, pre-approval requires a hard credit pull, which may slightly affect your score. Once complete, you’ll receive a pre-approval letter valid for about 60 to 90 days that confirms your buying power.
In Charleston’s competitive market, sellers often expect to see this letter before they’ll even consider your offer. It signals you’re not just browsing; you’re ready to close.
Key Differences at a Glance
| Feature | Pre-Qualification | Pre-Approval |
|---|---|---|
| Credit Check | Soft inquiry | Hard pull |
| Timeframe | Minutes to an hour | Up to 10 days |
| Verification | Self-reported | Documented |
| Seller Weight | Low | High |
| Validity | Varies | 60–90 days |
Pre-Qualification
- Credit Check
- Soft inquiry
- Timeframe
- Minutes to an hour
- Verification
- Self-reported
- Seller Weight
- Low
- Validity
- Varies
Pre-Approval
- Credit Check
- Hard pull
- Timeframe
- Up to 10 days
- Verification
- Documented
- Seller Weight
- High
- Validity
- 60–90 days
Why It Matters in Charleston’s Market
Charleston home prices remain elevated thanks to steady demand, historic charm, and limited inventory. With the Fed hinting at a rate drop, competition could heat up as more buyers re-enter the market. Having a pre-approval letter in hand gives you a serious edge, especially in popular neighborhoods like James Island, Daniel Island, and Mount Pleasant.
How Beaufort Lending Helps Local Buyers
Working with a local mortgage broker in Charleston can make the difference between winning and losing the home you want. Here’s what sets Benji Gecy and the Beaufort Lending team apart:
- Rates about 0.5% lower than the national average
- Closings in as little as 12–15 days fast enough to compete in multiple-offer situations
- 24/7 Instant Rate Quote tool so you can check your numbers anytime, day or night
Plan Your Next Move
- If you’re just exploring budgets, start with a quick pre-qualification.
- If you’re ready to make an offer, get pre-approved now, especially before rates dip and demand spikes.
- Use the Charleston Mortgage Calculator to estimate affordability.
- Get a 24/7 personalized Instant Rate Quote - Opens in Messenger in Messenger to see where you stand today.
Final Word
Pre-qualification helps you dream. Pre-approval helps you win. In Charleston’s fast-moving market, knowing the difference could be the key to unlocking the front door of your next home.
Ready to start? Connect with Beaufort Lending today and let our local experts guide you through the process.