
How Much Home Can You Afford in Myrtle Beach in 2026?
How Much Home Can You Really Afford in Myrtle Beach in 2026?
Buying a home in Myrtle Beach in 2026 is still achievable, but affordability now depends on more than just the purchase price. Monthly payments, debt to income ratios, insurance costs, and HOA fees all play a role in what fits comfortably into your budget.
This guide breaks down how much home you can realistically afford in Myrtle Beach based on income, loan type, and payment structure, including condo versus single family comparisons and coastal cost considerations.
Myrtle Beach Home Prices vs Income Reality
According to Zillow, Myrtle Beach home values have stabilized across much of the Grand Strand. This gives buyers more predictability than during the rapid price surge years.
Redfin reports longer average days on market, which gives buyers more negotiating power and time to run the numbers.
Debt to Income Limits by Loan Type
Your Debt-to-Income (DTI) ratio is one of the most critical numbers lenders look at. It compares your total monthly debt payments to your gross monthly income. Lenders use this percentage to gauge risk—essentially, do you have enough income left over after paying debts to handle a mortgage?
What is Included in Your DTI?
Many buyers are surprised to learn that DTI does not include your daily living expenses. Lenders focus strictly on contractual debts found on your credit report plus your new housing obligations.
- Included in DTI: Minimum credit card payments, car loans or leases, student loans, personal loans, child support or alimony, and your new total mortgage payment (including Principal, Interest, Taxes, Insurance, and HOA).
- NOT Included: Groceries, utilities (electric/water), cell phone bills, car insurance, gas, or streaming subscriptions.
How to Calculate Your DTI
You can estimate your back-end DTI (which includes all debts) using this simple formula:
- Add up your monthly debts: Combine your current minimum debt payments + the estimated full mortgage payment of the home you want to buy.
- Determine gross income: Use your monthly income before taxes are taken out.
- Divide and Multiply: (Total Monthly Debt ÷ Gross Monthly Income) x 100.
Example: If your debts plus new mortgage equal $2,500/month, and your gross income is $7,000/month, your math is 2,500 ÷ 7,000 = 0.357. Your DTI is 35.7%.
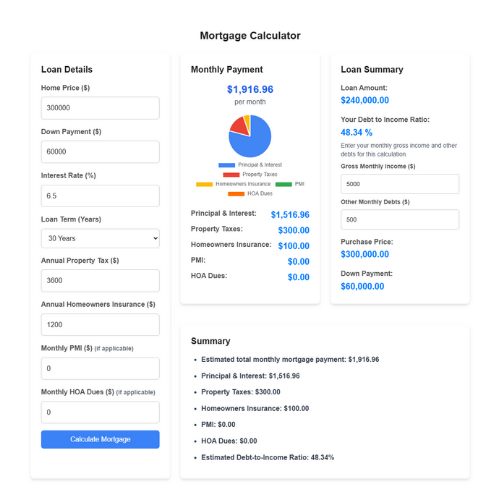
Use our Myrtle Beach mortgage calculators to test payments and check your DTI instantly.
Typical DTI guidelines
- Conventional loans: Often capped around 45% (sometimes up to 50% with strong credit).
- FHA loans: More flexible for first-time buyers, sometimes allowing up to 55-57%.
- VA loans: These focus more on "residual income" (money left over) rather than a strict DTI cap.
Condos vs Single Family Homes
Condos often come with lower prices but monthly HOA dues. Single family homes may cost more upfront but sometimes avoid HOA fees.
Coastal Insurance and HOA Costs
Why Work With Beaufort Lending
- Rates averaging 0.5 percent below the national average
- Fast closings
- Over 150 five star Google reviews
Get a Clear Affordability Plan
